
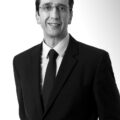
Paulo Sousa, CEO of Colep Packaging and President of Metal Packaging Europe
Colep Packaging operates in various segments of the metal packaging market. How does the company identify growth opportunities, and which markets do you consider most promising?
Colep Packaging operates with two substrates: aluminum and tinplate. Within these, we are focused on aerosols and the general line segment. Our focus is on consolidating our position in these markets where we have greater experience and presence. These are mature and stable markets. We do not anticipate strong growth; we expect them to evolve approximately at the pace of the economy. However, they remain fragmented from a supply perspective, which creates consolidation opportunities.
Furthermore, our customers are consolidating and require suppliers capable of offering a broader supply. What we are trying to do in Europe is precisely that: offer supply for various markets and geographies, covering Europe in a global manner and providing a more homogeneous service in these two major segments.
Are access to recycled materials and the availability of raw materials still among the main challenges? How is the industry addressing this situation?
It is one of the most difficult situations at the moment. The situation with trade wars and tariffs is causing significant market disruption, both in the availability of raw materials and in accessing them at economically viable prices.
Regarding recycling, it is still a relatively small market, and the supply of recycled material remains more expensive than using virgin material. The industry will have to grow to incorporate these products which, in theory, are part of a circular economy. However, metal has been circular for 100 years: we recycle steel and aluminum in enormous quantities, which is why we are champions of recycling within packaging.
How is Colep Packaging working to increase the sustainability of its products and processes?
We are primarily working on two major elements. We have an internal challenge that we summarize with one idea: “Making Life Easier”.
On one hand, we want to make life easier for the consumer, both industrial and private, by developing products that are simpler to use. On the other hand, we work on the entire manufacturing process to achieve savings and efficiencies.
We believe that sustainability is intimately connected with economic sustainability. One cannot exist without the other. Therefore, our developments are highly focused on reducing thicknesses, seeking alternative raw materials, reducing waste, and utilizing more efficient equipment.
For example, the latest equipment we have incorporated into one of our plants has an energy consumption of approximately 33% compared to a conventional equipment we previously had. The reduction of energy consumption is, therefore, a very important part of what we are doing.
Have you made other investments to improve not only sustainability but also Colep Packaging’s productivity?
Yes. For approximately four years, we have been making significant investments in the traditional business.
A significant portion has been allocated to changing equipment to reduce the thickness and, therefore, the weight of the packaging. We have also made modifications to production flows to achieve more efficient operations, reduce stages, and increase productivity.
Additionally, we have invested in a new aerosol assembly line as part of a project under the Recovery and Resilience Plan in Portugal, with the main objective of significantly reducing energy consumption. This line incorporates motors, solar panels, and other solutions that allow us to reduce energy consumption by approximately 66%.
We are also investing in both aluminum and tinplate in digitalization and digital printing. This allows us to produce certain formats more efficiently and bring new functionalities to the market.
Therefore, we are working on three main lines: thickness reduction and equipment optimization; more energy-efficient equipment; and digitalization, which adds value to marketing.
As President of Metal Packaging Europe, what do you consider to be the main challenges currently facing the European industry?
I believe the association has evolved very positively over the last few years. We have greater representation at the European level, increased involvement from members, and more active participation in the tasks we need to undertake.
At this moment, both the European Commission, the legislator, and the European Parliament recognize the role and contribution of the association.
However, if we talk about the challenges for European industry, the main problem is that European industry has stagnated for many years. Manufacturing outside Europe was widely used as a substitute for European manufacturing, and as a consequence, we have aging industries in some areas.
I don’t believe this is as prevalent in metal packaging, because several players in the European industry have continued to invest, and we have some of the latest lines and technologies available.
However, there is a problem in other links of the chain, especially in raw material production and other industrial segments.
There are several factors behind this loss of competitiveness: energy costs, labor costs, bureaucracy, and all the contextual costs associated with operating in the European Union.
Europe urgently needs an industrial revolution, but we are not progressing at the necessary speed. We are too slow, too dependent on political agreements, and have too many external dependencies.
What concrete advancements is the industry demanding to regain competitiveness?
All industrial sectors are working on this. European meetings involve sectors as diverse as chemical, steel, textile, and automotive, and specific plans exist for each. Furthermore, with the development of the defense industry, steel and aluminum are gaining even greater importance.
The problem is that isolated measures are often being taken. There is not yet a fully structured plan for the entire European industry.
Moreover, decisions are being made much faster outside Europe. The United States and Asia have a greater capacity for reaction than Europe. For me, the big problem is precisely this capacity for reaction: everything takes too long, and Europe lacks a true global industrial agenda.
What can the industry do? It can provide information and knowledge to help decision makers and policymakers make better decisions. That is precisely what we are trying to do.
The new European packaging and waste regulation proposes significant changes. What opportunities and challenges does it represent for metal packaging manufacturers?
I believe that such a regulation was necessary to bring greater homogeneity across the European Union. That is why it transitioned from a directive to a regulation, which allows for faster implementation and reduces dependence on each country’s interpretation. In that sense, I find it positive.
It also poses challenges, because it was developed at a time when sustainability held enormous weight, although it should always be connected to the economic dimension.
For the metal industry, one of the big challenges is that aluminum and tinplate have not been treated as permanent materials. In some ways, metal has been pushed to be considered worse than other materials, even though we already have a fully developed circular industry.
Therefore, the classification criteria for materials and substrates used in packaging are fundamental. That is one of the major challenges we face.
At the same time, there are great opportunities. Metal has a very high level of recyclability and can be reused multiple times. Even in certain models of packaging reuse, metal can make a lot of sense compared to other materials.
What role do you think metal packaging can play compared to other formats, especially in food?
The food industry is suffering greatly from the competition of multi-layer packaging, which is sometimes presented as more sustainable, although in reality, it is not necessarily so.
The recycling of multi-layer packaging can be practically non-existent and, therefore, does not contribute in the same way to a circular economy.
We need to work, and I hope that the legislation on Green Claims will also help, to clearly communicate the advantages of metal packaging over other alternatives.
There is a perception among consumers that we need to change. For example, some consumers think that everything they put in the yellow bin ends up being recycled. That is not the case. In the case of metal, the percentage recovered and recycled is very high, whereas for other materials, the situation is different.
We need to ensure that consumers have simpler and clearer information to make better decisions.
Here I see two major opportunities. On one hand, in certain types of packaging where metal is not yet as present, especially in reuse models. And on the other, in translating all the scientific knowledge we have into a discourse that consumers can easily understand.
We need to be able to explain that, in certain applications, choosing metal packaging can be a better option than choosing other types of packaging.
How do you think the European metal packaging market will evolve over the next five years?
If we can ensure that Extended Producer Responsibility (EPR) systems respect the characteristics of materials and effective recycling costs, and if we can ensure that the permanence and circularity of metal are recognized, I believe we will have a significant opportunity.
Furthermore, new regulations will likely significantly reduce the use of fossil-based plastics. This could lead to an increase in the price of plastics used in packaging, and in that scenario, metal will have a much stronger value proposition.
I see growth opportunities in both beverages and other segments. In beverages, for example, we are trying to move towards a can to can model, where packaging can be converted back into new packaging.
Technically, it is possible, especially for aluminum, and we also have a very developed recycling system for steel. There are countries where there is still room to significantly increase recycling rates.
Therefore, I do see growth opportunities. But there are also risks if we fail to ensure all of this is adequately recognized.
Currently, in much of Europe, EPR systems and the fees paid for recycling mean that metal is paying more than the actual cost of collecting and sending it for recycling. In some ways, metal is subsidizing other materials.
That needs to change. We hope that the new legislation will allow for the creation of a true level playing field, harmonizing systems and recognizing that different materials have distinct characteristics and, therefore, require different solutions.
I believe we are moving in that direction. The industry is doing important legislative advocacy work, and I believe we are being quite ethical and honest throughout this process.
From your experience as CEO and President, what qualities do you consider essential for leading an industrial company in such a changing environment?
I believe the most important thing a leader can do is to choose the right people to work with and give them clear direction.
You need to have a defined vision, be very ethical and transparent, and always tell the truth. Then you need to build a team aligned with that vision, capable of conveying it and making things happen.
I believe that at Metal Packaging Europe, we have managed to significantly strengthen the team and align it with what we want to achieve. Initially, we also worked on aligning all partners to define where we wanted to go. We made some important decisions, for example, to strengthen our advocacy activities and engage in trade issues.
When direction and objectives are clear, things start to work better.
Something similar happens at Colep Packaging. The metal packaging industry is constantly changing. Competition and a company’s history are no longer sufficient.
Furthermore, we have a significant challenge related to knowledge. Professionals with 35 or 40 years of experience are retiring, and we cannot allow that knowledge to be lost. We need to find new ways to transfer that knowledge.
As the leader of Colep Packaging, my responsibility is to provide a very clear vision. We must be ethical and transparent in our way of working and choose the right people.
As one moves up in an organization, they become more removed from day-to-day operations. How does that change the way one leads?
When you move from being on the ground to holding positions of greater responsibility, you have much less direct influence over what happens every day.
That is why you need to have very strong trust in people, accompanied by a very clear vision of where you want to go.
What I expect from my teams is that they can say: “I have these options, these are the pros and cons, and I am going to choose this one because I believe it is the best for the company.”
I believe that no one within an organization consciously makes a decision they know is worse for the company. Each person makes the decision they consider best with the information they have.
Therefore, my responsibility is to provide very clear direction so that they can make the best decisions and achieve the objectives we want to reach.
I cannot decide what a person on a production line will do today because I am not there, nor can I decide what a salesperson will do tomorrow with a client because I am not there either. But if people know where we want to go and what the company’s direction is, they can make better decisions.
What lessons from your professional career have most influenced your current way of making decisions and facing challenges?
Several things have stayed with me for a long time.
One comes from my father, who used to say that sales are 95% perspiration and 5% inspiration. Contrary to what many people think, not everything depends on being inspired or having talent. You have to work very hard.
You can have talent, but behind it there is always a lot of hard work. Things don’t happen by chance. That is the first lesson.
The second is that throughout my career, I have championed ethics and transparency. So far, it has worked for me, and I continue to believe it is the right path.
And the third is that we cannot achieve anything alone. Work is teamwork. We need to get people involved and work together.
Finally, I believe that often a bad decision is better than no decision at all.
Sometimes we want too much information before deciding and hide behind a lack of information to delay the decision. But in life and in business, there is always a certain level of risk, and we will never have all the information.
We will always make decisions with less information than we would like to have absolute certainty. But absolute certainties do not exist.
Is there any aspect you consider particularly important that we have not addressed?
I believe that trade and industrial policy are critical for the future, especially in the steel industry. For aluminum, I don’t see it with the same intensity right now, but we need to remain vigilant.
The industry is also starting to become more aware that we need to unite more. We are competitors in the market, but we also need to collaborate because there is external competition that can be too strong.
The good news is that metal packaging is here to stay. Consumers will continue to have very high-quality metal packaging in their homes for years to come.
The bad news, if we don’t do our job well, is that this metal packaging might not be manufactured in Europe.
And that is the real risk.
We need to work both to highlight the benefits of metal packaging and to highlight the benefits of manufacturing it in Europe.
If we manufacture in Europe, we are generating value and wealth for Europe. If products are simply consumed in Europe but manufactured elsewhere, we are destroying a significant part of European wealth.
That is the risk of current trade and industrial policies if we fail to implement them quickly enough.
 Metal Packaging Europe demonstrates its commitment to innovation and competitiveness following the success of its annual conference in Berlin
 INTERVIEW WITH ELISANGELA MATOS, SUSTAINABILITY DIRECTOR OF ARDAGH METAL PACKAGING IN BRAZIL
 Paulo Sousa appointed new president of Metal Packaging Europe (MPE)
 The key policy principles of the EPM for metal packaging recycling in Europe




0 Comments